Dubai Neighborhoods Explained: 9 Zones Compared on Price, Rent, Schools and Supply
By Gardener
In Dubai, lifestyle splits neighborhoods first and price splits them second. If you want to live by the metro and walk to things, you will look at the old town, the center and the coastal towers. If schools and parks come first, you will look at the central and southern communities. Then price: Q3 2026 average 1-bedroom resale figures run from about AED 950,000 in JVC to about AED 2.26 million in Downtown. Lumping all of that together as “a Dubai apartment” hides more than it tells you.
This guide maps the whole city. For a line-by-line cost comparison at around AED 1 million, see the JLT, Al Furjan and DSO walkthrough. For transport projects, see the Blue Line, Etihad Rail and new airport analysis.
How to read the numbers
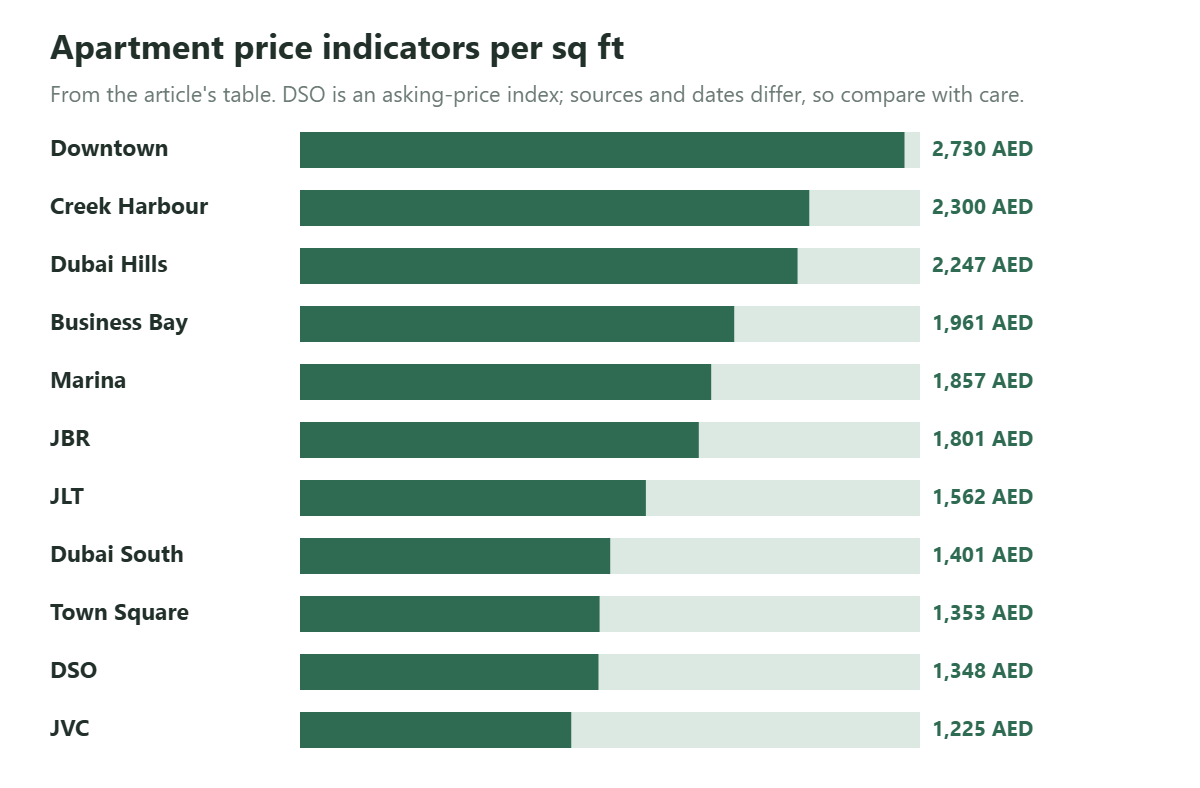
- Price per sq ft is for all apartments in an area, not 1-bedrooms alone. I could not verify a 1-bedroom-only index, so use the resale column for a 1-bedroom sense of price.
- Most resale prices and rents come from Metropolitan’s area reports (Q3 2026, or H1 2026 for Town Square). They are averages across buildings and sizes, not the price of any one unit.
- “Asking” means portal listing prices. Actual deals can be lower.
- Simple yield is average 1-bedroom rent divided by average resale price, before any costs.
- Supply pressure reflects whether Cushman & Wakefield Core named the area among those where construction is concentrated.
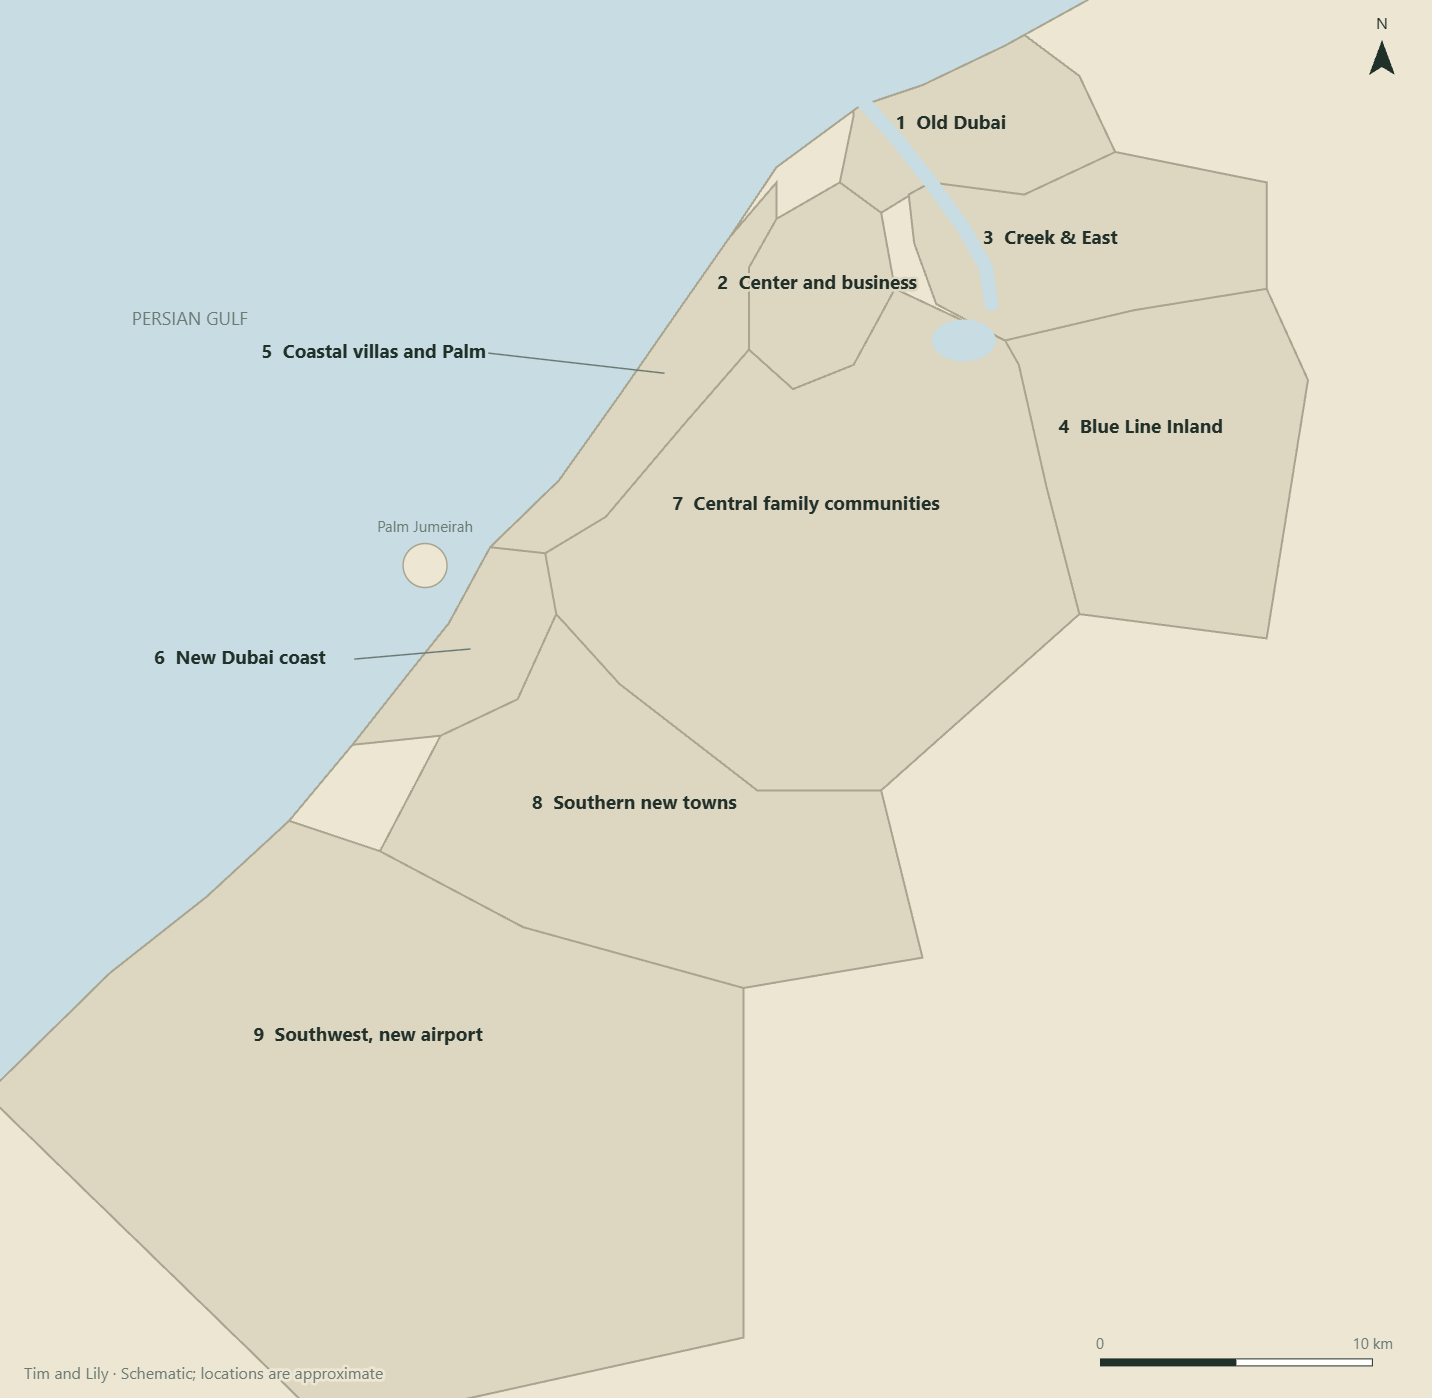
- The zones are my own grouping to make the city easier to grasp. They are not official districts.
The nine zones at a glance
| Zone | Main areas | Apartment AED/sq ft | 1-bed avg resale (AED) | 1-bed annual rent (AED) | Simple yield | Supply pressure |
|---|---|---|---|---|---|---|
| 1. Old Dubai | Deira, Bur Dubai, Karama, Al Garhoud | Not verified | Not verified | Deira 60,000–65,000; Karama 65,000; Bur Dubai 82,000 (asking) | Not verified | Not a named cluster |
| 2. Center and business | Downtown, Business Bay, DIFC | Downtown 2,730; Business Bay 1,961 | 2.26M; 1.53M | 108,000; 87,000 | 4.8%; 5.7% | High in Business Bay |
| 3. Creek and east | Creek Harbour, Al Jaddaf, Festival City, Mirdif | Creek Harbour 2,300 | 1.74M | 93,000 | 5.4% | Not a named cluster; check on-site launches |
| 4. Blue Line inland | DSO, International City, Academic City | DSO 1,348 (asking index); International City 700–850 | DSO 856,000 (asking) | DSO 63,400; International City 60,000 (asking) | DSO 7.4%; International City 8.5–10% (vendor) | Not a named cluster |
| 5. Coastal villas and Palm | Jumeirah, Umm Suqeim, Palm Jumeirah | Palm 3,490 (asking) | Not verified | Palm 169,000 (asking) | 3.5–7.3% across sources | Not a named cluster |
| 6. New Dubai coast | Marina, JBR, JLT, The Greens | Marina 1,857; JBR 1,801; JLT 1,562 | 1.50M; 2.14M; 1.27M | 89,000; 99,000; 80,000 | 5.9%; 4.6%; 6.3% | Not a named cluster |
| 7. Central family communities | Dubai Hills, MBR City, Al Barsha, Arabian Ranches | Dubai Hills 2,247 | 1.65M | Dubai Hills 90,000; Al Barsha 75,000 (asking) | Dubai Hills 5.5%; MBR City 4.5–5.5% (vendor) | High in MBR City |
| 8. Southern new towns | JVC, Town Square, Arjan, Sports City, Al Furjan | JVC 1,225; Town Square 1,353 | 947,000; 868,000 (H1) | 67,000; 60,000 (H1) | 7.1%; 6.9% | High in JVC and nearby Dubailand |
| 9. Southwest, new airport | Dubai South, Emaar South, Expo City, Jebel Ali | Dubai South 1,401 | 1.00M | 59,000 | 5.9% | High |
Dubai South shows why one number is never enough. Its report prints a 9.25% gross yield, far above the 5.9% simple calculation here. The average 1-bedroom price jumped 26% on just 44 deals in the quarter, so the mix of units sold may be driving the result.
Zone by zone
1. Old Dubai
The older commercial and residential districts along the Creek, with existing metro access and lower rents. Deira, Bur Dubai and Karama do not appear on Bayut’s freehold list, and a Q3 2026 Bayut report describes Deira as open to purchase only by locals and GCC nationals. Foreign buyers should check eligibility building by building. French and British schools in Oud Metha and Umm Hurair widen the options for families.
- Draws: metro, lower rents, markets and restaurants
- Watch: uneven building management, parking and traffic, ownership limits
2. Center and business
The finance and tourism core, on the Red Line axis. Prime does not mean immune: Downtown 1-bedroom rents fell 10.2% and 1-bedroom resale deals fell 47% in the Metropolitan report. Business Bay has about 9,400 units scheduled for 2026–27, according to Real Estate Club Dubai.
- Draws: short commutes, broad tenant demand, shopping and culture
- Watch: high prices and service charges (vendor figure for Downtown: AED 20–30 per sq ft)
3. Creek and east
Three very different places: Creek Harbour is Emaar’s waterfront tower community, Festival City pairs a mall with housing, and Mirdif is an older villa neighborhood. The Blue Line is planned to serve all three. Creek Harbour 1-bedroom rents fell 5.1% in Q3, even as 1-bedroom rental contracts rose 12%.
- Draws: access to DXB and the center, the waterfront, Deira International School in Festival City
- Watch: years of construction before opening, competing supply within communities. I found no reliable current figure for Mirdif prices.
4. Blue Line inland
DSO mixes a business park with housing, Academic City clusters universities, and International City draws demand with low rents. All three have Blue Line stations planned, but DSO has no metro station today. One vendor analysis reports the DSO asking index down 12.64% year on year as of June 2026.
- Draws: entry prices, lower service charges (vendor figure for DSO: AED 7–12 per sq ft), transport change in 2029
- Watch: vendors describe DSO as mainly leasehold, so confirm tenure on the title deed; International City building management varies
5. Coastal villas and Palm
Jumeirah and Umm Suqeim are long-established villa districts; Palm Jumeirah is an artificial island of beachfront apartments and villas. High-fee schools such as Kings’ School and Dubai College are close. Palm yields range from 3.5% to 7.3% depending on the source, which tells you how much unit size and sample matter.
- Draws: beaches, schools, low density
- Watch: high prices and service charges, car dependence in many spots
6. New Dubai coast
High-rise districts popular with expat professionals, built around the Red Line and a beach or lake promenade. Location did not prevent correction: JBR’s price per sq ft fell 13% year on year and Marina’s fell 4.2%.
- Draws: walkable daily life, public transport, a deep rental market
- Watch: service charges (vendor figure for Marina: AED 18–22 per sq ft), building age and repair costs vary widely
7. Central family communities
Dubai Hills is a large master community with parks and a mall, Al Barsha is an older district dense with schools and shops, and MBR City is newer development with about 11,800 units scheduled. Several highly rated international schools sit in and around Al Barsha.
- Draws: schools and parks, main-road access, family-size homes
- Watch: Dubai Hills 1-bedroom rents fell 4.4% while prices remain high; visit at school-run hours to judge traffic
8. Southern new towns
Low- and mid-rise communities at lower price points. Town Square, launched by Nshama in 2015, has parks and cycling trails but no metro inside the community, so a car is close to essential. JVC has about 18,500 units scheduled for 2026–27 with JVT, and about 74% of that pipeline is studios and 1-bedrooms, according to one vendor count.
- Draws: entry price, newer buildings, community living
- Watch: small-unit supply; a vendor estimates 20–25 minutes to Downtown from JVC and 25–30 from Town Square
9. Southwest, new airport
Logistics and industrial zones, Expo City and the future airport site. Route 2020 reaches Expo City. Dubai South and the Expo corridor have about 14,200 units scheduled, and one vendor rates schools as “limited but growing.” Emaar South shows a median of AED 1,750 per sq ft on DXBinteract, but that is measured on a different basis from the area average above.
- Draws: new buildings, airport and logistics employment
- Watch: a vendor estimates 35–45 minutes to Downtown at peak hours; amenities take time to fill in
Schools by zone
Most ratings reported in the press rest on 2023–24 KHDA inspections. Gulf News reports that KHDA said no formal inspections would take place in 2025–26. Fees below are as reported in the press, and I have not checked each school’s own fee sheet. Check the grade you actually need, and budget separately for transport, uniforms and books.
| Zone | School | Curriculum | KHDA rating | Annual fees (AED) |
|---|---|---|---|---|
| Old Dubai | Dubai English Speaking School (Umm Hurair) | British primary | Outstanding | 43,084–53,320 |
| Old Dubai | Lycée Français International (Oud Metha) | French | Outstanding | 29,488–62,363 |
| Creek and east | Deira International School (Festival City) | IB, British | Outstanding | 44,616–89,889 |
| Blue Line inland | GEMS Wellington Academy DSO | British, IB | Very Good | 40,340–89,246 (2025–26; not re-verified) |
| Blue Line inland | Dubai English Speaking College (Academic City) | British secondary | Outstanding | 84,326–90,633 |
| Coast | Kings’ School Dubai (Umm Suqeim) | British | Outstanding | 47,179–71,801 |
| Coast | Dubai College (Al Sufouh) | British secondary | Outstanding | 97,415–110,305 |
| Near New Dubai | Dubai British School Jumeirah Park | British | Outstanding | 65,719–111,799 |
| Near New Dubai | Dubai International Academy Emirates Hills | IB | Outstanding | 44,979–79,696 |
| Central | JESS Arabian Ranches | British | Outstanding | 54,129–104,544 |
| Central | Kings’ School Al Barsha | British | Outstanding | 57,999–105,873 |
| Central | GEMS Dubai American Academy (Al Barsha) | American | Outstanding | 66,185–93,300 |
| South | Victory Heights Primary (Sports City) | British primary | Outstanding | 40,138–54,733 |
| South | JSS International School (JVC) | Indian | Very Good | 17,214–41,513 |
Waitlists and bus routes rarely appear in public tables, so ask each school directly.
Where to start looking
This table is about how you want to live, not what might earn a return.
| Your priority | Start with zones | Also check |
|---|---|---|
| Young children, parks and community living | 7, 8 | School buses, how many cars you need, waitlists |
| A specific secondary curriculum | Choose the school, then nearby zones | Places and fees for that grade |
| Living without a car | 1, 2, 6 | The real walking route to the station, in summer too |
| Keeping rent down | 1, 4, 8, 9 | Commute time and other running costs |
| Frequent flying | 3, 4 | When flights may shift to the new airport |
| Commuting to Abu Dhabi too | 8, 9 | Access to the Etihad Rail station and the timetable |
Four assumptions worth dropping
- “High yield means a good neighborhood.” Headline yields can run high where prices are low or repair costs are heavy.
- “Same neighborhood, same price.” Age, management and floor change a lot. Do not use an area average as a building’s value.
- “Near the metro line means walkable.” The line, the station entrance and a usable footpath are three different things.
- “Freehold area means foreigners can buy any unit.” Leasehold or restricted property can exist in the same area, so check each building.
Before you choose
- School rating, fees and places for your child’s grade
- Actual travel time at weekday school and work hours
- Building completion year, management company and the state of common areas
- Ownership type and tenancy terms
- Cooling costs, service charges and other fixed bills
- Distance and hours for groceries, clinics and places of worship
- Exit terms if regional events change your plans
Market context
The Arabian Post, reporting ValuStrat’s Q3 data, puts the average resale price at AED 1,627 per sq ft, down 4.4% on the quarter and 1.5% on the year. ValuStrat also said overall home values had adjusted by about 10% since regional conflicts began. All the zone figures above were collected during this correction and may change.
Sources
Press
- Khaleej Times, Dubai school fees 2026–27
- Khaleej Times, fees at Outstanding KHDA schools
- Gulf News, 23 Outstanding schools
- Gulf News, Very Good schools and fees
- Gulf Business, 1-bedroom rents under AED 80,000
- Gulf Today, Bayut Q3 2026 report
- Khaleej Times, supply concentration in five communities
- The Arabian Post, ValuStrat Q3 data
Industry and vendor
- Metropolitan area reports: Downtown, Business Bay, Creek Harbour, Marina, JBR, JLT, Dubai Hills, JVC, Town Square H1, Dubai South
- ValuStrat, June 2026 market data
- dubizzle, H1 2026 rental report
- Global Property Guide, UAE yields
- AiGents Realty: yields by area, yields and charges compared, service charges
- Real Estate Club Dubai: 2026–27 supply, price per sq ft, DSO, JVC, Dubai South, Town Square
- Betterhomes: Town Square, Silicon Oasis
- Bayut, freehold areas
- DXBinteract, Emaar South
Photo: Dubai skyline 2015 (crop), Tim.Reckmann, CC BY-SA 3.0. Resized. Charts and maps by Tim and Lily.